What Sets Me Apart?
I care about what you’re going through, and I understand that mortgage trouble often comes as a result of a difficult life change. I bring clarity by reviewing your paperwork with you, explaining what’s happening in plain English, and answering your questions patiently so you can understand your options without pressure or embarrassment. With more than 200 successfully completed short sales, I’m here to help—and as your Realtor, I’m on your side, representing your interests and keeping you informed every step of the way.
Testimonial quote Testimonial quote Testimonial quote Testimonial quote
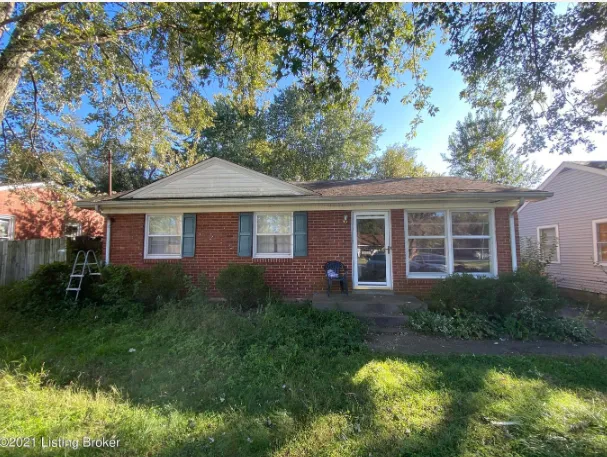
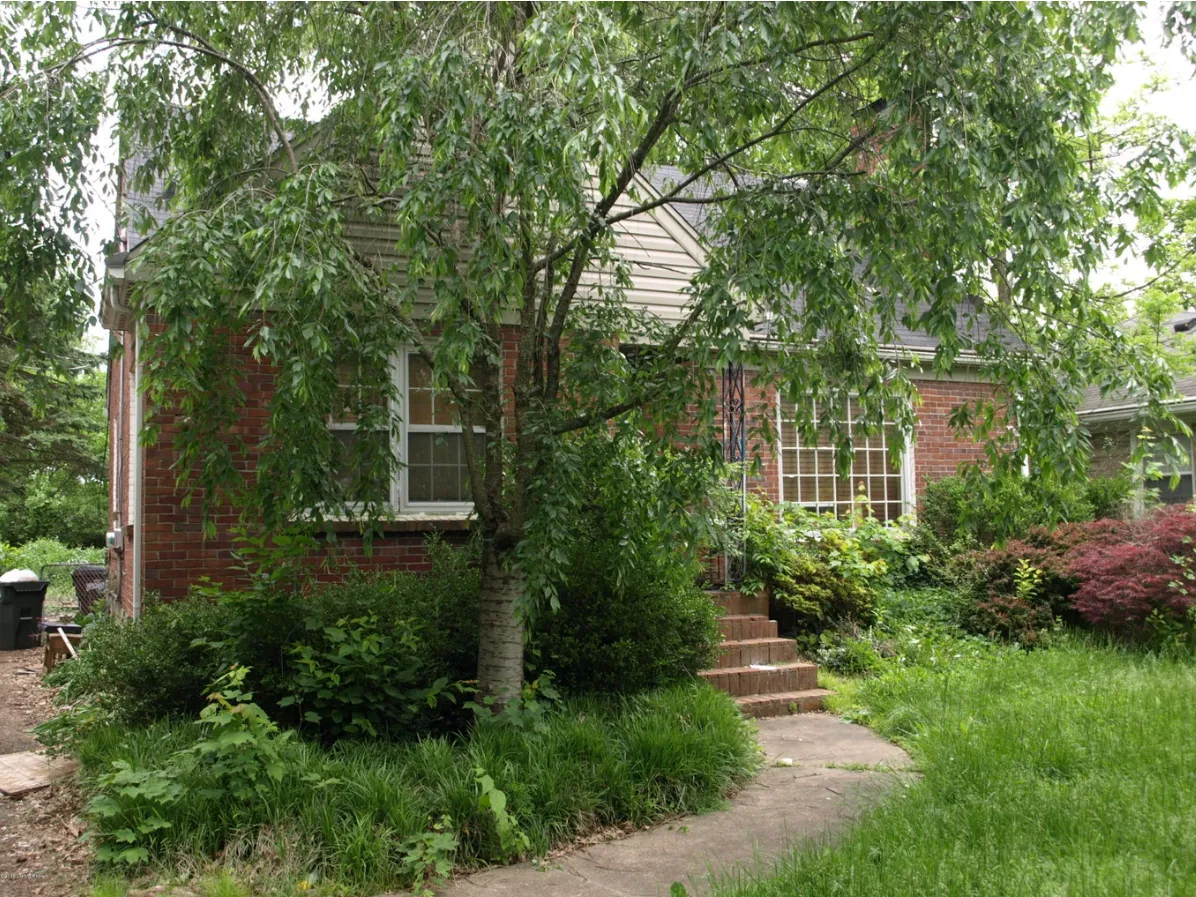
Actual Homes Saved From Foreclosure by David Halpern
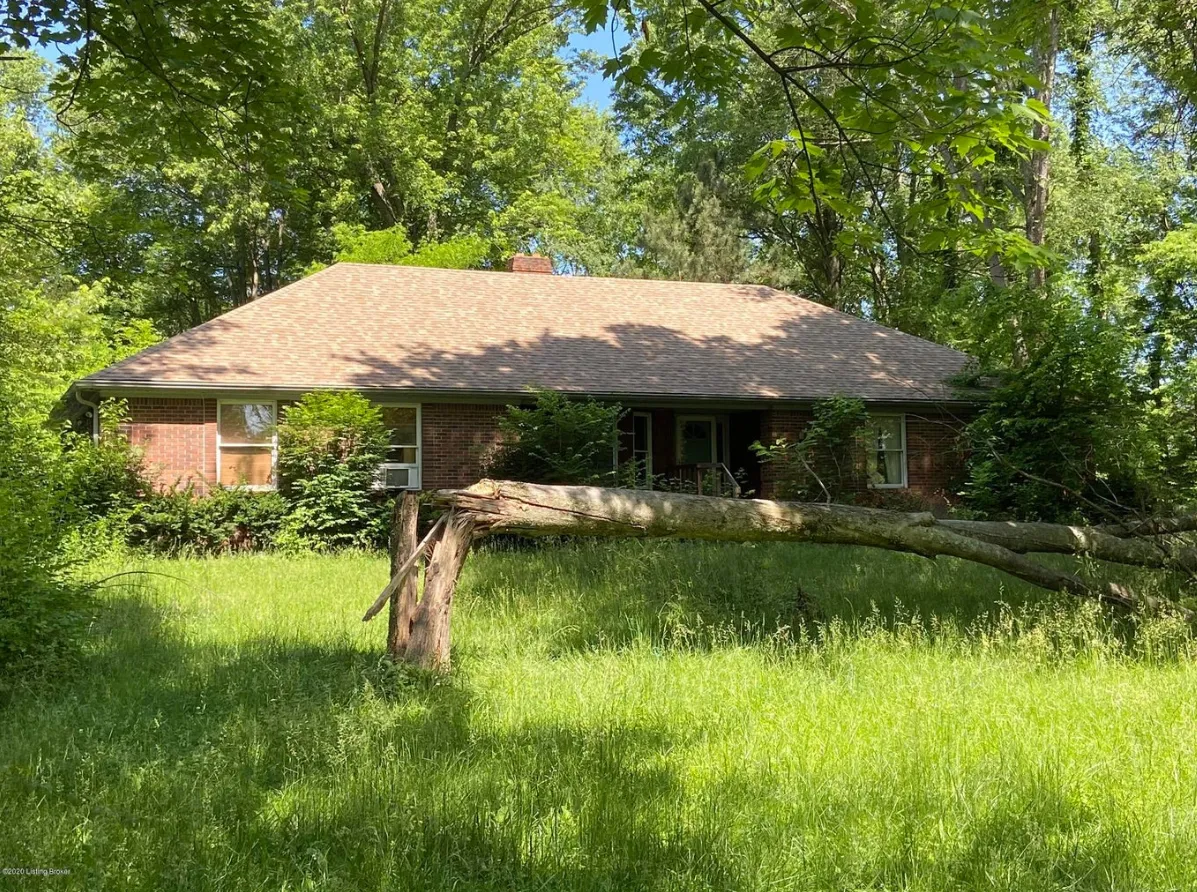
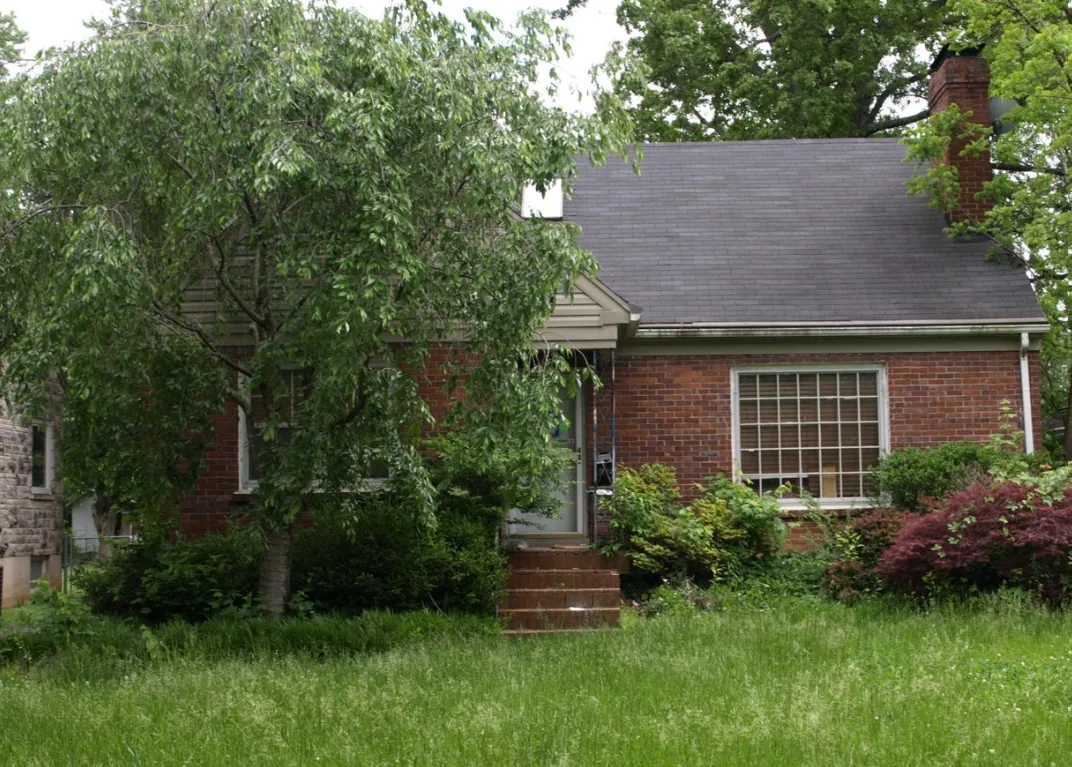
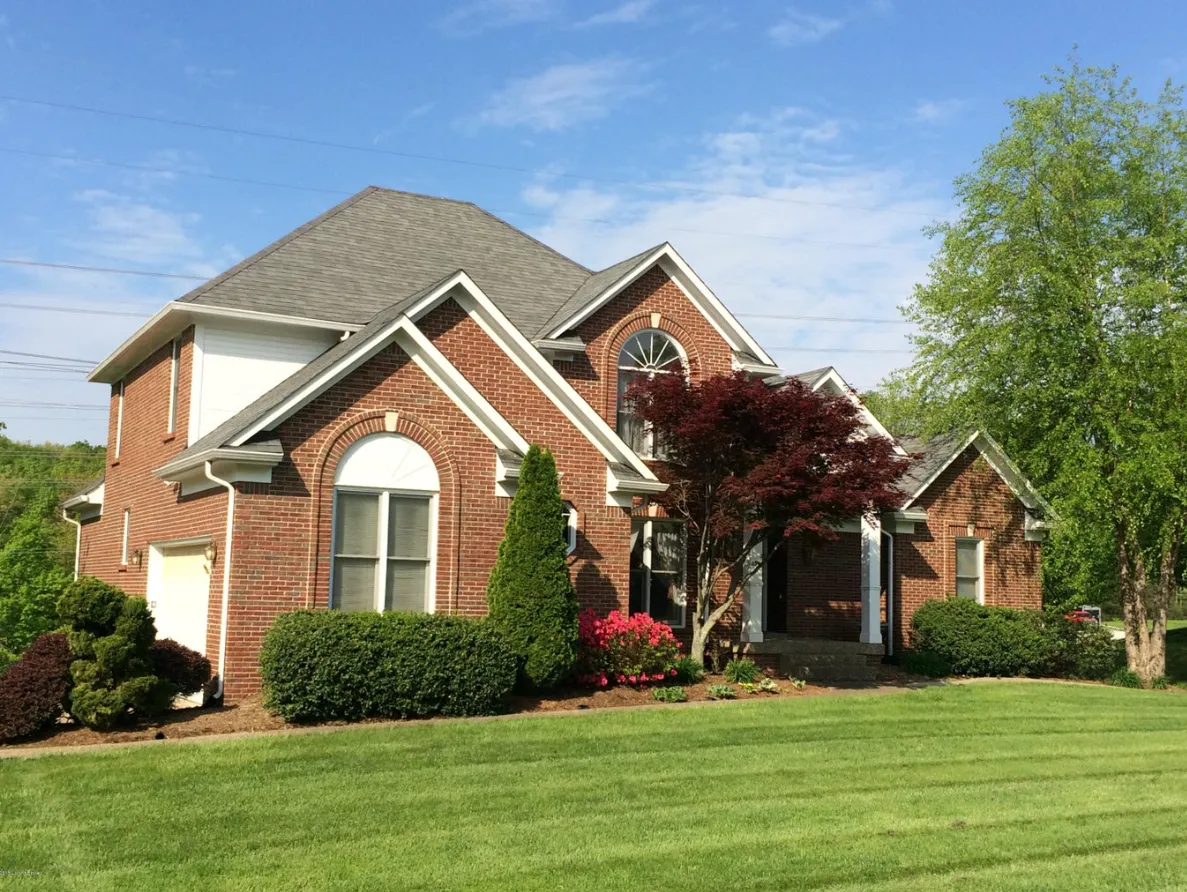
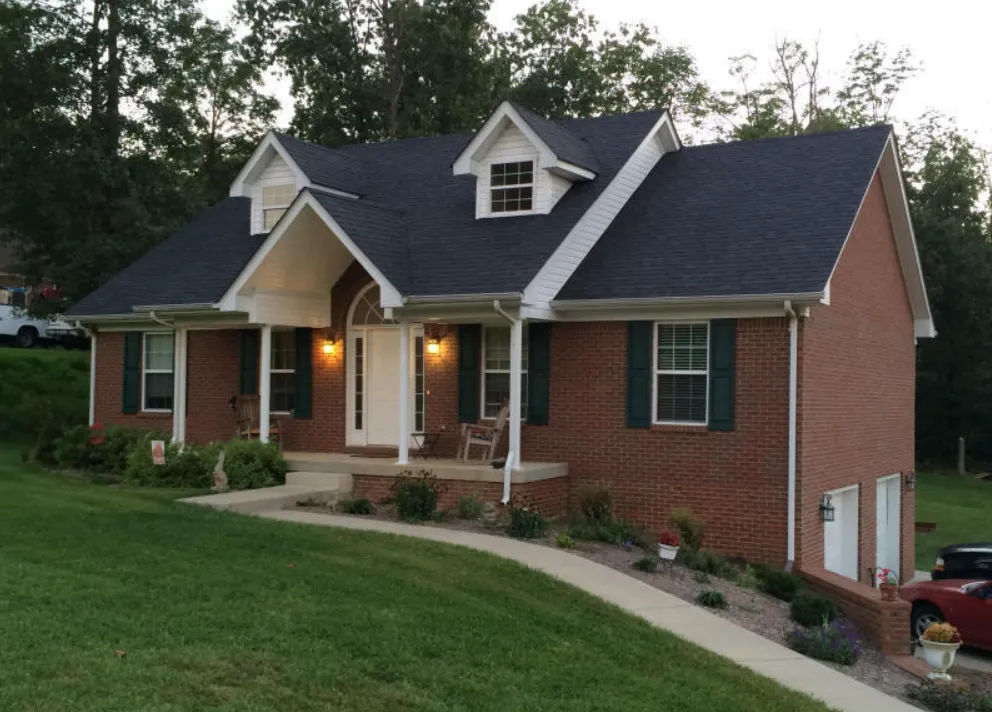

Stop and Avoid Foreclosure
Can I Stop Foreclosure
Stop Foreclosure Without Bankruptcy
Stop Foreclosure Last Minute
Do I need a Foreclosure Attorney
Stop Foreclosure Now
How To Stop Foreclosure Immediately
Sell Your House with a Short Sale
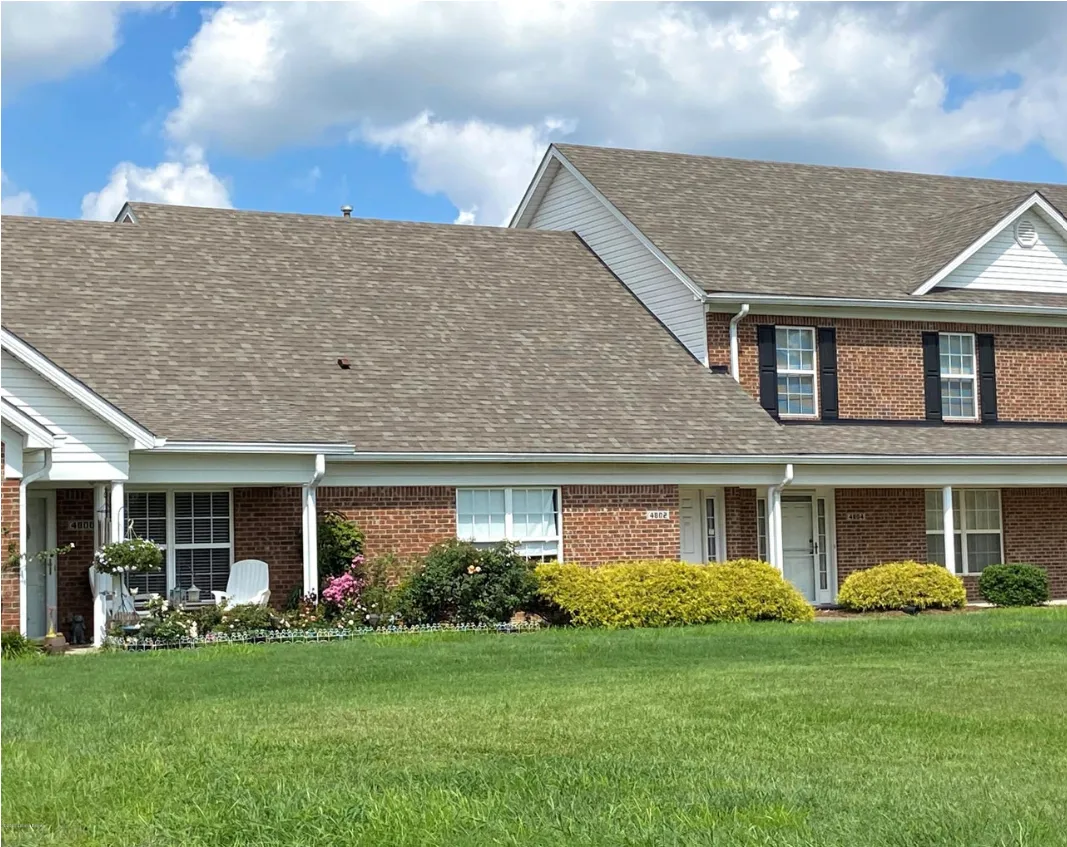
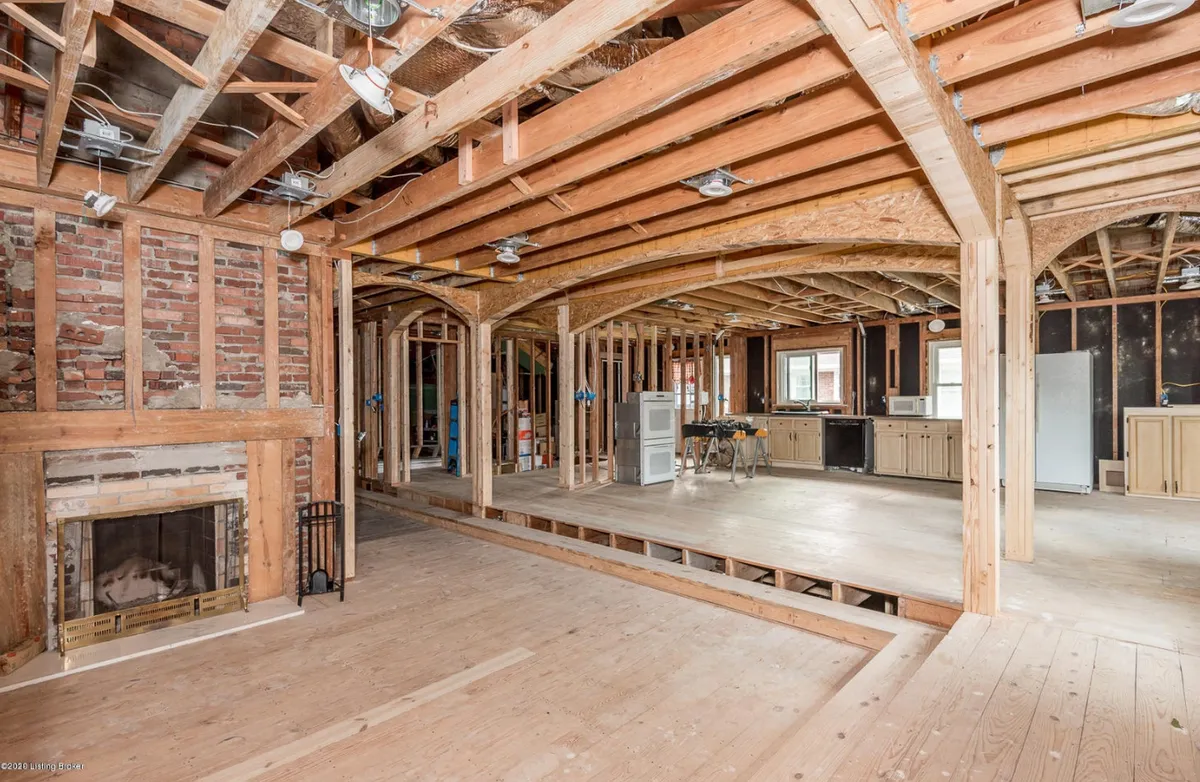
Where Do We Start?
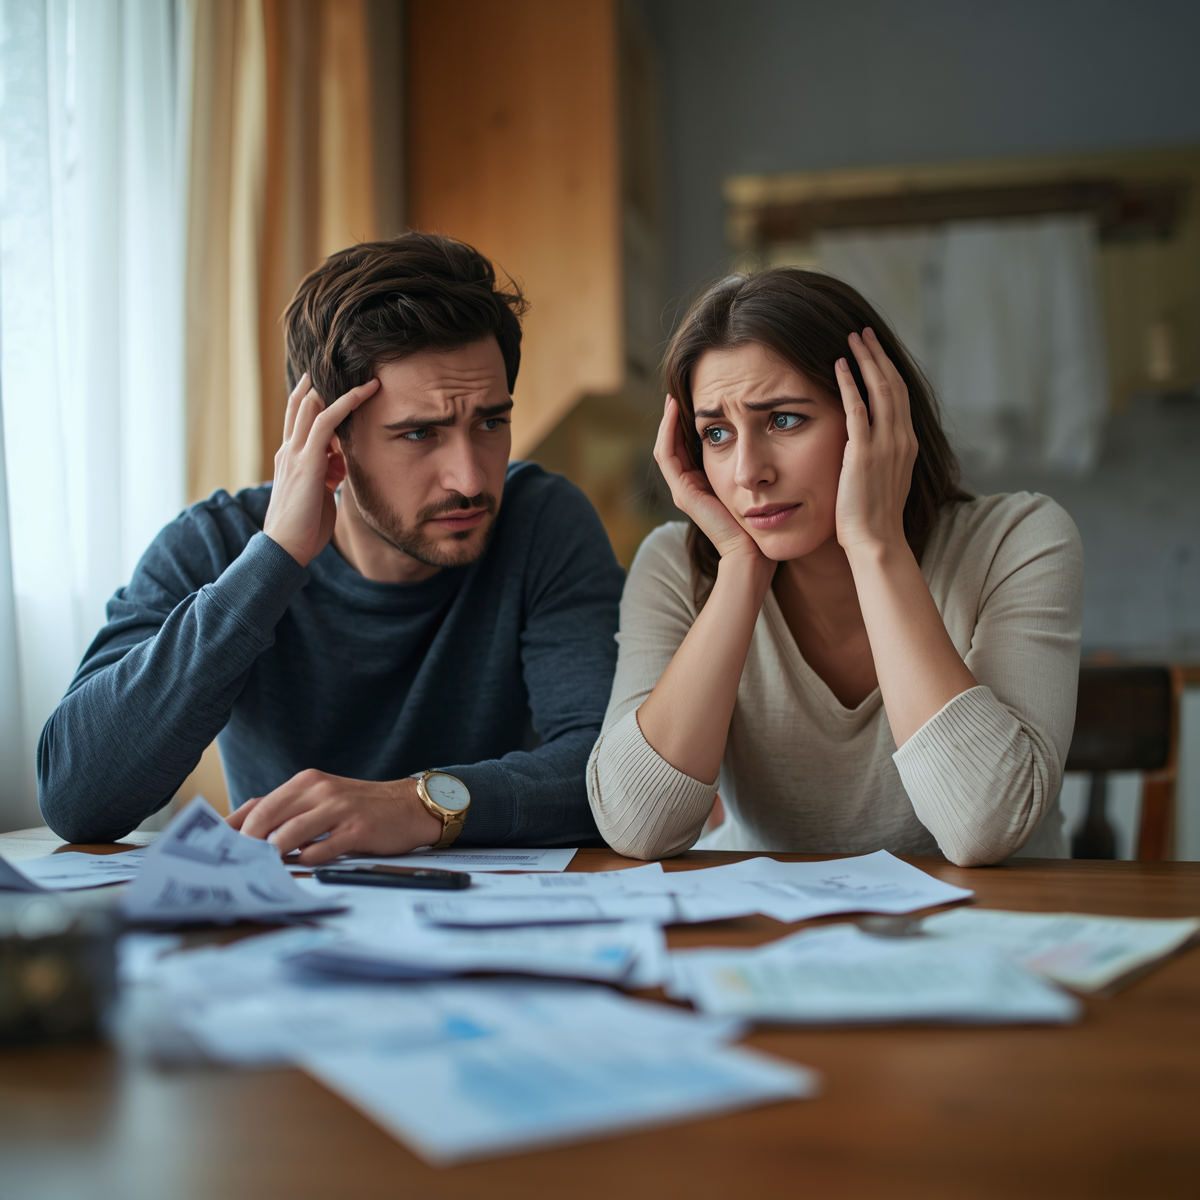
You may have a stack of letters on your kitchen table and a mortgage payment you can’t make. Maybe you’ve tried selling your house already. Maybe you’re worried about where your family would go.
You can call me while you’re still figuring out what to do.
I’m Dave Halpern. I help homeowners in Louisville and the surrounding communities sell their homes, including through short sales when that is the appropriate path. Our first conversation starts with what’s happening in your life and what you need help understanding.
First, tell me what’s worrying you
You might be thinking, “How did we get here? We’ve worked hard. We’ve tried to do the right thing.”
Pat and Carrie McCarty described those feelings in a letter after I helped with their short sale. When they first contacted me, they were worried, embarrassed, overwhelmed, and losing sleep.
If that sounds familiar, tell me. You can talk openly about the missed payments, the house, and the circumstances that brought you here. I’ll listen and ask questions so I can understand what you’re facing.
In a short sale, your lender pays the Realtor fees. You do not.
Too many sellers let their house get lost to foreclosure because they can't afford the Realtor commission and other closing fees. They are surprised when I assure them that their lender covers the Realtor and closing fees on your behalf.
When I ask your lender to approve a short sale, the lender understands the financial reality. The sale won’t bring in enough to pay off your mortgage, and if you can’t afford to make up that difference, you don’t have extra money to pay my commission and other closing costs out of pocket.
Your lender wants to recover as much of the mortgage debt as possible. If a short sale offers a better financial outcome than foreclosure, the lender has a reason to help the sale go through.
That’s why it can approve paying my commission and other closing costs, such as title fees and property taxes, from the buyer’s purchase money at closing. The lender receives what’s left after the approved costs are paid.
We’ll look at your own paperwork together
When we meet, bring your mortgage statement and any letters or other documents you’ve received from your lender or its attorneys. Bring whatever you have, even if it’s disorganized.
I’ll go through it with you and explain the mortgage and sale information in plain English. If a question needs an attorney’s answer, I’ll help you identify what to ask.
When I met with the McCartys, we spent four hours reviewing their documents and talking through the process. Every meeting is different. I want you to have time to ask questions and understand what we’ve discussed.
“He was very calm, organized, and knowledgeable. He did not pressure us in any way. This helped calm our fears and skepticism.”
— Pat and Carrie McCarty.
We’ll talk about what selling could look like for you
You may owe more than you think the house could sell for. You may have two mortgages. You may have had the house on the market for months without an offer.
We’ll look at your situation and discuss whether a sale, including a possible short sale, makes sense to explore. I’ll explain the steps involved, what I would handle, and what I would need from you.
Ashley Knight wrote that my staff and I “gave us options we never knew existed.”
You deserve time to understand those possibilities and decide how you want to proceed.
When you hire me, I represent you. I am on your side.
As your Realtor, I handle the sale and work with your mortgage company through the short sale process. The home sells to an independent buyer, typically represented by another Realtor.
I am not an investor trying to buy your house cheap. I am your real estate agent looking out for your best interest. I work to attract the highest offer for your home. If the highest offer still doesn't cover what you owe, I work with your lender to accept an amount short of your payoff and typically they forgive the shortfall. That's why they call it a short sale.
You can keep asking questions
When we meet, bring your mortgage statement and any letters or other documents you’ve received from your lender or its attorneys. Bring whatever you have, even if it’s disorganized.
I’ll go through it with you and explain the mortgage and sale information in plain English. If a question needs an attorney’s answer, I’ll help you identify what to ask.
When I met with the McCartys, we spent four hours reviewing their documents and talking through the process. Every meeting is different. I want you to have time to ask questions and understand what we’ve discussed.
“He was very calm, organized, and knowledgeable. He did not pressure us in any way. This helped calm our fears and skepticism.”
— Pat and Carrie McCarty.
Let’s start with a conversation
Tell me what prompted you to visit this page and what you’re most concerned about. We’ll start there.
[Talk With Dave]
Behind on Your Mortgage? Facing Foreclosure? You May Have More Options Than You Think.
Experienced Short Sale and Foreclosure-Related Real Estate Help in Louisville, Kentucky
Are you behind on your mortgage payments? Worried about foreclosure? Have you received foreclosure papers and don't know what to do next?
Perhaps you've lost your job, are going through a divorce, or have experienced illness, disability, or another financial hardship that makes it difficult to keep up with your mortgage.
You may feel overwhelmed, embarrassed, or afraid that you're about to lose your house and everything you've invested in it.
I understand how frightening these situations can become.
Before you give up on your house, give away your equity, or accept a quick cash offer, let's talk.
I'm David Halpern, a Louisville REALTOR® with more than 200 successfully completed short sales. I help homeowners understand their real estate options when they're behind on mortgage payments, facing foreclosure, or struggling to afford their homes.
Whether you have substantial equity or owe more than your house is worth, there may be solutions worth exploring.
No judgment. No pressure. Just an honest conversation about your situation and your options.
What's Happening With Your Mortgage or House?
Every homeowner's circumstances are different. Choose the situation that best describes what you're experiencing.
I'm Behind on My Mortgage Payments
You've missed payments, or you're worried that you won't be able to make upcoming payments.
[Understand Your Options]
I've Received Foreclosure Papers
You've been served with a foreclosure lawsuit and are frightened about what happens next.
[Learn About Foreclosure in Kentucky]
I'm Considering a We Buy Houses Cash Offer
An investor has offered to buy your house quickly, but you're not sure whether the price is fair.
[Learn How to Protect Your Equity]
I Owe More Than My House Is Worth
You need to sell, but you're concerned that the sale won't produce enough money to pay off your mortgage.
[Learn About Short Sales]
My House Needs Repairs I Can't Afford
Your house needs maintenance, cleaning, or repairs, and you don't have the money to prepare it for sale.
[Learn About Selling As-Is]
I'm Concerned About an Aging Parent's House
Your parent may be struggling with mortgage payments, property taxes, confusing financial notices, or managing the family home.
[Help for Seniors and Their Families]
You Don't Need to Be Embarrassed About Your Financial Situation or the Condition of Your House
Financial hardship can happen to anyone.
Job loss, reduced income, divorce, illness, disability, and unexpected expenses can make it difficult to keep up with mortgage payments and home maintenance.
Sometimes a homeowner falls behind on repairs because there simply isn't enough money.
In other situations, people become overwhelmed and stop maintaining the house because they're dealing with more immediate problems.
I've seen homes in all kinds of conditions, and I understand that difficult life circumstances can affect anyone.
You don't have to clean, declutter, paint, or make repairs before calling me.
You don't need to apologize for your house, either.
I'm not there to judge you or your home. I'm there to understand your circumstances and help you explore possible solutions.
Depending on your property's condition, market demand, and the terms buyers will accept, selling your house as-is may be a practical option.
You may be surprised to learn that some buyers are willing to purchase properties needing substantial repairs.
Let's talk before you spend money you may not need to spend.
[Can I Sell My House Without Making Repairs?]
Just Received Foreclosure Papers? Don't Panic, But Don't Ignore Them.
Being served with foreclosure papers can be frightening.
Many homeowners assume that once the bank files a foreclosure lawsuit, they've already lost their house and someone will soon arrive to force them to leave.
Receiving foreclosure papers in Kentucky does not mean your house has already been sold or that eviction is imminent.
Kentucky generally uses a judicial foreclosure process involving several legal stages before a property is sold at auction.
The process can take months, although the timeline varies according to the circumstances and how far the case has progressed.
You may still have opportunities to explore mortgage assistance or selling your house before the foreclosure sale.
However, court deadlines are serious. If you've received foreclosure papers, promptly consult a qualified Kentucky attorney about responding to the lawsuit.
You should also contact your mortgage servicer to discuss available assistance.
Understanding where you are in the foreclosure process is an important first step toward making an informed decision.
[What Happens After I Receive Foreclosure Papers in Kentucky?]
Don't Give Away Your Home Equity Because You're Afraid of Foreclosure
If you're behind on payments or facing foreclosure, you may have received offers from companies advertising:
We Buy Houses for Cash!
Close in Days!
Sell As-Is!
No Repairs Needed!
Choose Your Moving Date!
These offers can be attractive when you're worried about losing your house.
Some investors provide legitimate services, and a quick cash sale may be appropriate in certain situations.
But here's something many homeowners don't realize:
You can be several months behind on your mortgage, facing foreclosure, and still have substantial equity in your home.
I've personally encountered situations where frightened homeowners accepted deeply discounted investor offers because they believed foreclosure was imminent and they had no other options.
In some cases, homeowners could potentially have received tens of thousands of dollars more by listing their property for sale, even after paying real estate commissions and customary selling expenses.
I've seen situations where the potential difference exceeded $100,000.
Before accepting a cash offer, it's worth comparing:
What your house may be worth in its present condition.
How much you owe on your mortgage and other obligations.
What you could potentially receive through a traditional sale after expenses.
How much time is realistically available.
The advantages and disadvantages of each selling option.
Before you sign away your equity, let's review the numbers.
[Should I Sell to a We Buy Houses Company or List With a Realtor?]
Can I Sell My House If I Owe More Than It's Worth?
Yes, it may be possible.
Sometimes homeowners owe more on their mortgage than their house can reasonably sell for.
They assume they can't sell because they don't have the money to pay the difference.
There may be an option called a short sale.
A short sale occurs when a mortgage lender agrees to allow a property to be sold even though the proceeds will be less than the outstanding mortgage balance.
For example, you might owe $250,000 on your mortgage, but your house may only be worth $210,000.
The mortgage company may agree to approve the sale even though it will receive less than the amount owed.
Short sales require lender approval, and the requirements vary depending on the mortgage and the homeowner's circumstances.
One particularly important consideration is what happens to the unpaid mortgage balance.
In some approved short sales, the lender agrees to forgive the remaining debt. Any such deficiency waiver should be clearly documented in writing.
With more than 200 successfully completed short sales, I understand the additional work, documentation, and lender coordination these transactions can require.
[Learn How a Short Sale Works]
What Happens If I Just Walk Away From My House?
When mortgage payments become overwhelming, some homeowners stop communicating with their mortgage company, abandon the property, or simply wait for foreclosure.
They may believe that once the bank takes the house, their mortgage debt automatically disappears.
Unfortunately, that's not necessarily true.
In Kentucky, a mortgage lender may have the right to pursue a deficiency judgment when the foreclosure sale doesn't produce enough money to satisfy the debt.
That means losing the house does not automatically eliminate the remaining mortgage obligation.
If you have equity, selling before foreclosure may allow you to preserve some of that money.
If you owe more than your property is worth, a properly negotiated short sale with a written deficiency waiver may help resolve the remaining mortgage obligation.
Before walking away from your house, find out what alternatives may still be available.
[What Happens If I Let My House Go Into Foreclosure?]
Worried About an Aging Parent's House or Finances?
Sometimes financial problems involving a home develop gradually, particularly when an older homeowner is having difficulty managing bills, understanding notices, or maintaining the property.
Perhaps the spouse who always handled the finances has passed away.
Maybe an adult child or someone with power of attorney is responsible for paying the bills, but important payments have been missed.
In other situations, illness, disability, cognitive changes, or declining income may make managing the household increasingly difficult.
Even a house that's completely paid off can be at risk if property taxes remain unpaid.
When property taxes are no longer collected through a mortgage escrow account, the homeowner must arrange to pay them directly.
Unpaid property taxes can eventually result in liens, collection proceedings, and even foreclosure.
This can be especially concerning when an older homeowner has accumulated substantial equity over many years.
I specialize in helping Louisville-area seniors and their families navigate real estate decisions, including situations involving financial hardship, downsizing, and the sale of longtime family homes.
When appropriate, and with the homeowner's permission or proper legal authority, I can work with adult children and other professionals to help coordinate the real estate aspects of a possible transition.
A lifetime of accumulated home equity deserves careful protection.
[Learn About Protecting an Aging Parent's Home]
Why Work With David Halpern?
More Than 200 Successfully Completed Short Sales
I've spent years helping Louisville-area homeowners navigate complicated real estate transactions involving mortgage difficulties, financial hardship, and foreclosure.
A short sale can involve considerably more work than an ordinary real estate transaction.
There may be multiple mortgage loans, property liens, hardship documentation, lender negotiations, property condition issues, and deadlines associated with foreclosure proceedings.
I've successfully completed more than 200 short sales and understand the additional procedures these transactions can require.
But experience involves more than knowing how to process paperwork.
I understand that behind every financially distressed property is a person or family dealing with difficult circumstances.
When you contact me, I'll listen, ask questions, and help you understand the real estate options that may be available.
If you have equity, we'll explore how different selling options could affect your estimated net proceeds.
If you owe more than your house is worth, we'll discuss whether a short sale might be appropriate.
If your goal is to remain in your home, I can direct you toward mortgage assistance resources and qualified professionals who can help you investigate those possibilities.
And if you're an older homeowner or an adult child helping a parent, I understand the additional family, financial, and logistical considerations that may be involved.
You deserve clear information, respect, and an opportunity to make an informed decision.
[Learn More About David Halpern]
Questions Louisville Homeowners Frequently Ask
I'm behind on my mortgage payments. What should I do?
Contact your mortgage servicer promptly and ask about available assistance. Depending on your situation, options may include repayment arrangements, loan modifications, or selling the property. An experienced Realtor can help evaluate the real estate alternatives.
Can I sell my house if I'm already in foreclosure?
Possibly. A foreclosure lawsuit doesn't automatically prevent you from selling your property. Your options depend on the stage of the proceedings, mortgage payoff requirements, other liens, and whether the sale can be completed in time. Consult a Kentucky attorney about legal deadlines.
Do I have to repair my house before selling it?
Not necessarily. Some buyers are willing to purchase houses in their existing condition. Contact me before spending money on repairs or renovations. We can discuss what buyers may accept and what preparation, if any, makes financial sense.
Can I sell my house if I owe more than it's worth?
You may qualify for a short sale if your mortgage company agrees to approve a sale for less than the outstanding mortgage balance. The lender's approval and treatment of the remaining debt are important considerations.
Should I accept an offer from a We Buy Houses company?
Before accepting, compare the cash offer with what you might receive from a traditional sale after commissions, closing expenses, and other costs. A cash offer may be convenient, but that convenience sometimes comes at a significant discount.
Can my parents lose their paid-off home because of unpaid property taxes?
Yes. In Kentucky, unpaid property taxes can lead to liens and collection proceedings that may ultimately result in foreclosure. Families should investigate unpaid tax notices promptly and explore possible payment arrangements, legal assistance, or selling options.
Can the bank pursue me for money after foreclosure?
In some circumstances, yes. Kentucky law permits deficiency judgments when a foreclosure sale doesn't satisfy the mortgage debt. Whether a particular homeowner remains liable depends on the circumstances and applicable law.
What if a family member responsible for my parent's finances hasn't been paying the bills?
First, determine which payments have been missed and whether any legal deadlines are approaching. With the homeowner's permission or appropriate legal authority, family members may be able to help gather information and coordinate next steps. If financial exploitation is suspected, consult an appropriate attorney or protective agency.
[See More Questions and Answers]
Free Guide for Louisville Homeowners
Behind on Your Mortgage? Facing Foreclosure?
7 Things to Know Before You Give Up on Your House or Accept a Cash Offer
I've prepared a free educational guide to help homeowners understand important considerations when they're struggling with mortgage payments or worried about foreclosure.
You'll learn about:
What happens when mortgage payments are missed.
Why receiving foreclosure papers doesn't necessarily mean immediate eviction.
How to determine whether your house has equity.
What to consider before accepting a cash offer.
Selling a house that needs substantial repairs.
How short sales work.
Practical steps to help you evaluate your options.
[Download My Free Homeowner's Guide]
Let's Talk About Your Situation
If you're behind on payments, worried about foreclosure, uncertain about a cash offer, or concerned about an aging parent's house, I'm available to talk.
You don't need to get your house ready before contacting me.
You don't have to be embarrassed about your financial circumstances.
And you don't have to decide to sell before we talk.
I'll listen, help you understand the real estate options that may be available, and discuss practical next steps.
Before you give up on your house, give away your equity, or accept a cash offer, let's talk.
David Halpern, REALTOR®
Louisville, Kentucky
More Than 200 Successfully Completed Short Sales
Serving Louisville, Jefferson County, Oldham County, Bullitt County, Shelby County, Spencer County, and surrounding communities.
[Schedule Your Free, Confidential Consultation]
[Call David Halpern]
Important information: This website provides general educational information and real estate services. It does not provide legal, tax, or financial advice. Foreclosure timelines, short-sale approvals, deficiency waivers, and selling outcomes depend on individual circumstances. David Halpern does not guarantee that a lender will approve a short sale or postpone foreclosure. If you have been served with foreclosure papers or face a property tax foreclosure, promptly consult a qualified Kentucky attorney about your legal rights and deadlines.
Add a Title
Add paragraph text. Click “Edit Text” to update the font, size and more.
To change and reuse text themes, go to Site Styles.

Who We Are
Meet Fin Advisory
Fin Advisory is a leading financial consultant dedicated to providing top-notch financial services. With a focus on accuracy and efficiency, we aim to simplify the tax process for our clients, ensuring compliance and maximizing returns.
How We Help
Financial Services
At Fin Advisory, we offer a wide range of professional accounting services. From tax preparation to financial consulting, our dedicated team is here to assist you every step of the way.
Retirement Planning
Investment Management
Budgeting & Debt Reduction
Tax Strategies
150+

Businesses
Helped
40+

Combined Years
of Experience
16

Financial
Experts

How We Help
Clients' Voices
Testimonials from our satisfied clients.
John Clark
"Fin Advisory made filing my taxes a breeze. Their attention to detail and personalized service exceeded my expectations."
Elizabeth Johnson
"I highly recommend Fin Advisory for their professionalism and expertise. They helped me navigate complex tax issues with ease."
Michael Wim
"Fin Advisory provided me with valuable tax advice that saved me money. Their team is knowledgeable and dedicated to client satisfaction."
Why Fin Advisor?
Frequently Asked Questions
Clear answers to help you make confident financial decisions.
What types of clients do you work with?
We work with individuals, families, and small business owners who want to take control of their finances and plan for the future. Whether you’re just starting out, preparing for retirement, or managing complex investments, our advisors can help.
How do I get started with Fin Advisory?
Simply schedule a free consultation through our contact page or give us a call. We’ll discuss your goals, review your current situation, and outline a personalized strategy to help you move forward.
Are your financial plans customized?
Yes — every financial plan we create is tailored to your unique goals, lifestyle, and risk tolerance. We don’t believe in “one-size-fits-all” advice, so you’ll always receive strategies designed just for you.
Do I need a large investment to work with you?
Not at all. We work with clients at all stages of their financial journey. Whether you have a modest savings account or a substantial portfolio, we’ll help you create a plan that maximizes your resources and builds toward your goals.
Get Started
Want to work with us?
Let’s create a personalized financial plan that puts your goals within reach — starting today.

COMPANY
LEGAL
SOCIALS
Copyright 2026. Dave Halpern Real Estate Agent. All Rights Reserved.
Copyright Dave Halpern Real Estate Agent, Inc. 2026 All Rights Reserved, David Halpern, Real Estate Broker
Dave Halpern is a licensed Realtor and Real Estate Broker in the Commonwealth of Kentucky.
We are not lawyers, tax advisors or mortgage brokers.
© 2026 All rights reserved. Dave Halpern Real Estate Agent, Inc.